
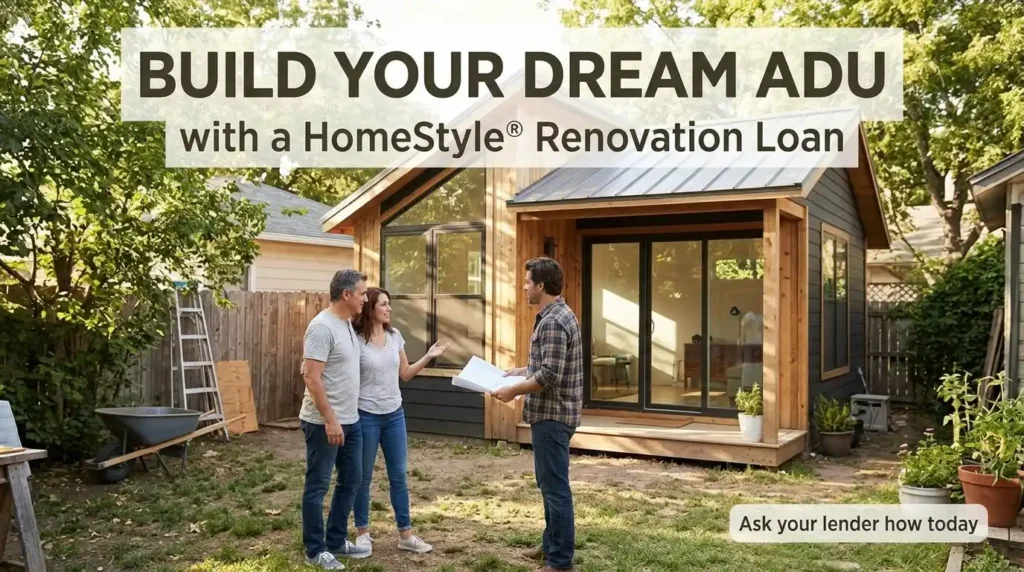
Yes, a HomeStyle Renovation loan can pay for a new ADU. Fannie Mae says buyers and owners refinancing a one-unit home can use it to construct or install an accessory unit, and its program FAQ confirms the unit may be detached. The catch: the money arrives inside a new first mortgage, with strict paperwork and a completion deadline.
That combination makes HomeStyle one of the few conventional loans that can carry a backyard cottage from drawings to move-in, and also one of the more demanding. This article covers only what Fannie Mae publishes, then weighs the advantages and drawbacks for an ADU in the Puget Sound area. For every other way to pay for a unit, see our side-by-side guide to ADU financing.
How HomeStyle Folds the Unit Into Your Mortgage
HomeStyle Renovation is a conventional mortgage that combines a home purchase, or a refinance of the home you own, with the cost of improving it. There is one application, one closing and one monthly payment.
The refinance version is a limited cash-out refinance. You do not walk away with cash; the new loan pays off the old one and funds the planned work. Fannie Mae’s FAQ confirms this also works on a home with no mortgage at all, as long as no money is returned to the owner at closing.
The loan is sized against the property’s as-completed value. An appraiser uses the plans and specifications to estimate what the home will be worth once the work is finished, and the lender measures the loan against that figure rather than against today’s value. Fannie Mae also caps renovation costs as a share of that value, so the project and the property have to stay in proportion.
What Fannie Mae Says About Accessory Units
New Units, Including Detached Ones
Fannie Mae’s ADU product page states that borrowers who purchase or refinance a one-unit property and want to construct or install a new ADU can use a renovation loan to finance it. The HomeStyle FAQ adds that an accessory unit may be detached from the primary dwelling, provided it meets local codes and the Selling Guide’s ADU requirements.
What Counts as an ADU for the Loan
The Selling Guide describes an ADU as a living area independent of the primary dwelling that can be added to it, created within it or detached from it. The unit needs its own kitchen, sleeping area, bathroom and bathing facilities and a separate entrance, and it must be subordinate in size to the main home. The appraiser checks these points.
What the Program Will Not Build
The same FAQ says HomeStyle funds may not be used to construct another residential dwelling on the property, and that tearing down and rebuilding the home is not allowed. The line Fannie Mae draws is between an accessory unit and a second full house, so the design should clearly read as accessory to the main home.
How Many Units a Lot Can Carry
Fannie Mae’s standing property rules allow a single ADU on a one-unit home. A December 2025 announcement extended eligibility to one-unit properties with more than one ADU, but only for lenders that have adopted its newer appraisal policy. Washington cities generally must allow two ADUs per lot, so ask early which policy your lender follows if a second unit is part of the plan.
Advantages for a Backyard Cottage
The Finished Property Supports the Loan
Because the loan rests on as-completed value, a homeowner with modest equity today may still reach a workable budget, provided the appraisal of the finished property supports it.
A Detached Unit Is Not Ruled Out
Unlike FHA’s renovation program, which our 203(k) guide for ADU projects explains is limited to attached new units, HomeStyle does not require the new unit to touch the house.
Early Costs Can Be Paid at Closing
Fannie Mae now lets lenders release part of the renovation budget at closing for materials, permits, design services or deposits already paid to the contractor. Its FAQ also confirms that a documented contractor deposit paid before closing can be reimbursed then.
Beyond Owner-Occupied Homes
The Selling Guide lists one-unit second homes and one-unit investment properties among eligible properties, not only principal residences. Confirm with the lender how that applies to an ADU on a home you do not live in.
Drawbacks to Weigh Before You Apply
Your Existing Mortgage Is Replaced
A HomeStyle refinance pays off your current first mortgage. If that loan carries a rate well below today’s market, the whole balance moves to the new rate, which is the same trade-off we walk through in our article on giving up a low rate to build.
A Firm Completion Window
The renovation loan agreement sets a deadline for finishing the work, measured from closing, with only limited extensions for extenuating circumstances while payments stay current. A permitted backyard unit has to fit inside that window, so permits should be in hand before closing.
More Documents, Fewer Lenders
The borrower and contractor must sign a binding renovation contract before closing that itemizes the work, names subcontractors and sets a payment schedule. Plans and specifications must come from a licensed or certified contractor, a renovation consultant or an architect, and changes need a formal change order request. Not every lender offers HomeStyle, and fewer have closed one with an ADU.
Little Room for Do-It-Yourself Work
Owner labor is allowed only at the lender’s discretion, on one-unit properties, for a small share of the value and with reimbursement for materials only.
From Closing to Final Inspection: How the Money Moves
Renovation funds sit in a custodial account managed by the lender or its agent. After any amount released at closing, further draws follow completed work: the lender must order periodic inspections confirming the work matches the plan before issuing more money, and payment goes out by joint check or by wire with the borrower’s written consent.
At the end, the lender needs a certification that the work matches the plans, an appraiser’s completion report, a title update showing no mechanics’ liens, lien waivers or a clean title report, and a certificate of occupancy where local rules require one. The draw logic resembles a construction loan, which our article on how ADU construction lenders release funds covers in more detail.
HomeStyle, FHA 203(k) and CHOICERenovation Side by Side
For an ADU, the clearest difference between HomeStyle and the FHA 203(k) is the detached unit: HomeStyle’s FAQ allows one, while HUD limits a newly added 203(k) unit to one attached to the house. HomeStyle also reaches beyond owner-occupants, while the 203(k) is built for primary residences.
Freddie Mac’s CHOICERenovation is the other conventional option; Freddie Mac says it can finance building a brand-new ADU as well as reworking an existing structure, such as an old garage, barn or shed, into one.
Can Rent From the New Unit Help You Qualify?
Fannie Mae’s ADU rental income rules are written for purchases and limited cash-out refinances of a one-unit home with an ADU, supported by the appraiser’s rent analysis. Whether rent from a unit that does not exist yet can count on a HomeStyle file is a question for your lender; plan as if your current income must carry the loan. Our breakdown of ADU rent and loan qualification compares the major programs.
Homeowners HomeStyle Tends to Suit
Buyers who want to purchase a home and add a backyard cottage in the same transaction.
Owners whose current mortgage rate offers no advantage over today’s market, or who have no mortgage at all.
Owners with thin equity today but a project the as-completed appraisal is likely to support.
It suits less well when the existing mortgage rate is valuable, when the owner wants to start before permits are issued, or when much of the work would be done by the owner.
Pairing HomeStyle With a Design-Build Contractor
Fannie Mae requires the borrower, not the lender, to choose the contractor, and the lender then verifies that the contractor is licensed, qualified and financially able to finish. Because United Signature does not make loans, its part is to deliver what the lender reviews: a signed contract, plans and specifications, a line-item budget and a schedule that fits the completion window. Bring the lender’s checklist to the first meeting, and look at United Signature’s current financing options for finishes or extras outside the mortgage.
FAQ
Does a HomeStyle loan require me to be buying a house?
No. It works with a purchase or with a limited cash-out refinance of a home you already own, including one with no mortgage, as long as you receive no cash back at closing.
Can design and permit fees be covered by a HomeStyle loan?
Yes. Fannie Mae lists permits, plans and specifications, architect and design fees and inspection costs among financeable renovation costs, and part of the budget can be released at closing for those early items.
What happens if the ADU is not finished before the HomeStyle deadline?
The lender may grant a limited extension for extenuating circumstances if the loan is current; otherwise Fannie Mae can require other remedies. Build the schedule with the permit already issued so the window is not consumed by review.
Can I build the ADU myself with HomeStyle financing?
Not as the main builder. Fannie Mae requires a licensed contractor chosen by the borrower, and only a limited amount of owner work is permitted, with the lender’s approval and reimbursement for materials alone.
Does HomeStyle require a contingency reserve on a one-unit home?
Fannie Mae does not require one on a one-unit property, though a lender may set one up. Unused contingency funds go toward reducing the loan balance unless they are applied to documented additional improvements.