
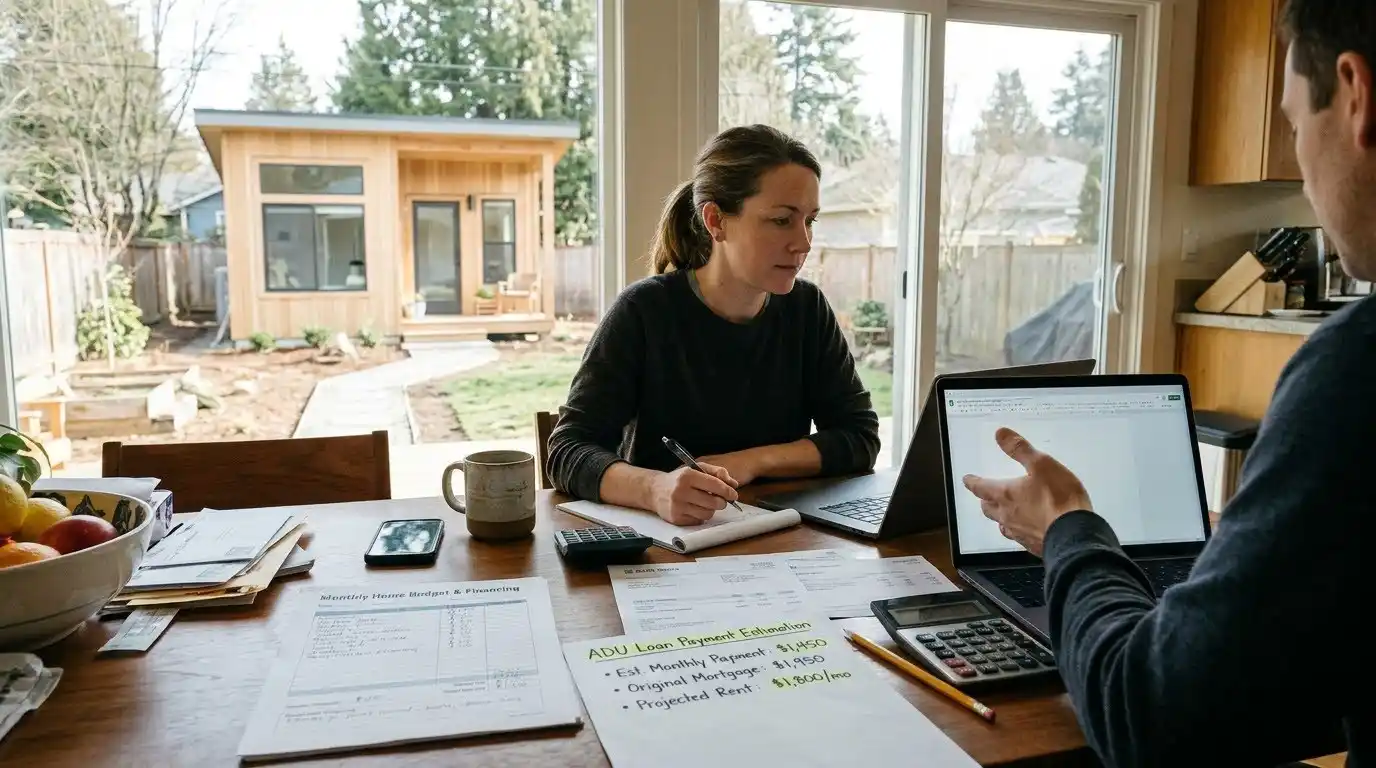
Your monthly payment on an ADU comes from four inputs: how much you borrow, the interest rate, the length of the loan and whether you pay interest only or principal and interest. During construction the payment usually climbs as more money is drawn. After move-in, add insurance, property tax changes, utilities and maintenance for the true monthly cost.
This guide shows how each input moves the payment, how the number changes between the build and the years after it, and how to test it against a rising rate. Every illustration here is in words, because rates and terms shift too often for fixed examples to stay accurate. For the products themselves, see our ADU loan options compared.
The Four Inputs Behind Any Loan Payment
The Amount You Actually Borrow
Start with the contract price, subtract the savings you will put in, and add what the loan must also carry: a contingency for surprises, and any closing costs or fees you choose to finance. The result, not the contract price, is the figure to estimate with.
The Interest Rate, Fixed or Variable
A fixed rate keeps the payment steady for the life of the loan. A variable rate moves with an index, so your estimate is only valid for the rate in force today. When comparing offers, look at the annual percentage rate as well, since it folds certain fees into a single cost figure.
The Length of the Repayment Term
A longer term spreads principal over more months and lowers each payment, but you pay interest for longer, so the total cost rises. A shorter term raises the payment and cuts the total.
Interest-Only or Amortizing
An interest-only payment covers just the interest on the current balance and leaves the principal untouched. An amortizing payment covers interest plus a slice of principal, so the balance falls every month. Many ADU financing plans move from the first kind to the second at some point, and that switch is often the biggest change in the monthly number.
How Each Input Pushes the Payment Up or Down
Borrowing twice as much, at the same rate and term, roughly doubles the payment. Amount is the most direct lever, which is why trimming scope or adding savings changes the estimate faster than anything else.
A higher rate lifts the payment, and the effect is stronger on long terms, because interest makes up a larger share of each early payment.
Stretching the term lowers the payment, but by less than you might expect. Making a term half again as long cuts the payment by less than a third, because interest keeps accruing over the added years.
Switching from interest-only to amortizing raises the payment even when the rate and balance stay exactly the same.
The Build Phase and the Years After Move-In
While the ADU is under construction, money usually goes out in stages. On a HELOC or a construction loan, you typically pay interest only on what has been drawn so far, so the payment starts small and rises with each draw. Our explanation of phased ADU payments shows how those stages line up with invoices.
After completion, the picture changes. A construction loan converts to a permanent mortgage or is paid off, and payments begin to include principal. A HELOC keeps its interest-only option until the draw period ends, then shifts to repayment. Map both phases separately: one estimate for the months of construction, one for the period after the unit is finished. The details of draws and conversion are explained in how ADU construction financing works.
A cash-out refinance behaves differently. You start paying on the full new balance right after closing, before most of the work is done, so there is no small early phase to plan around. The broader trade-offs of that route are in our guide on whether to refinance for an ADU.
Testing the Payment Against Higher Rates
If any part of your financing has a variable rate, calculate the payment three ways: at today’s rate, at a moderately higher rate and at a clearly higher one. Choose the higher scenarios yourself rather than relying on a forecast, and pick levels that would make you uncomfortable rather than ones that feel likely.
Then check two things. First, whether the highest scenario still fits your budget without counting any rent from the unit. Second, what happens when that higher rate meets the switch from interest-only to amortizing, which is when the two effects stack. The way a home equity line moves from its draw period into repayment is covered in our HELOC guide for ADU owners.
If the stressed payment does not fit, adjust before you sign: borrow less, lock part of a variable balance at a fixed rate where the lender allows it, or choose a product with a fixed payment.
Costs That Arrive With the New Unit
Homeowners insurance usually needs to be updated to cover the new dwelling, and a rented unit may call for a different policy. Ask your agent before construction ends so the change is not a surprise at renewal.
Property taxes generally rise once a finished ADU is added to the assessed value of the property. The county assessor sets the timing and amount, so treat it as a line item to confirm locally.
Utilities for the unit, if they are not on a separate account paid by an occupant, add to your monthly costs, especially through the darker, wetter months of a Puget Sound winter. Ask early whether the unit will have its own meters, since that decides who pays.
A maintenance reserve, set aside every month, keeps future repairs from turning into new debt. Appliances, roofing, exterior paint and flooring all wear out on their own schedules.
Two Scenarios Described in Words
Picture a homeowner who funds the cottage with a home equity line. In the first months, only the deposit has been drawn, and the payment is modest. By the final trade, the balance is close to the full project cost and the payment has stepped up several times. When the draw period later ends, the payment rises again as principal is added. Insurance and tax increases arrive around move-in, and rent, if any, starts later still.
Now picture a homeowner who chose a cash-out refinance. The payment jumps to its new level right after closing and stays there, predictable but immediate. The carrying costs arrive at the same point after completion. The second plan is simpler to budget but heavier at the start; the first is lighter early but changes more over time.
Getting a Reliable Number From Lenders and Calculators
Online calculators are useful for comparing scenarios, but most of them assume a fixed rate and an amortizing loan from the first month. They usually leave out property tax, insurance, any mortgage insurance and the interest-only phase.
Ask each lender for a written estimate of the payment in each phase, including the draw period and the repayment period for a credit line. For most mortgages, the standardized Loan Estimate you receive after applying shows the projected payments and closing costs in a consistent format, which makes side-by-side comparison easier. Check whether your quoted rate depends on your credit tier, because the same loan can be priced differently for two applicants.
Turning the Estimate Into a Go or No-Go
Add the loan payment for each phase to the carrying costs, then compare the total with your income without any rent from the unit. If it fits with room to spare, the plan is resilient. If it only fits once a tenant moves in, build a cash cushion that covers the months before that happens; the timing tools in our build-now, pay-later guide can help bridge that gap. Once you have a number you trust, review the current partner offers on the ADU financing page and bring both to your first project conversation.
FAQ
Should I count expected rent when deciding what payment I can afford?
Treat rent as a bonus in the first estimate. Size the payment to your current income, then see how much faster you could pay down the balance or rebuild savings once rent arrives.
Does paying extra principal during a HELOC draw period lower later payments?
Usually yes. Extra principal reduces the balance, and the repayment-period payment is calculated on whatever balance remains when the draw period ends.
Why is the lender’s estimate higher than my online calculator result?
The lender often includes property tax, insurance, mortgage insurance or the actual rate for your credit tier, while a basic calculator shows only principal and interest at an assumed rate.
How often can the payment on a variable-rate line change?
It depends on the agreement. Some lines adjust with each billing cycle, others less often, so read the adjustment terms and any rate caps before you sign.
Is the minimum payment on a promotional balance enough to plan around?
Rarely. The minimum may not clear the balance before the promotional period ends, so divide the balance by the months remaining and plan to pay at least that amount.