
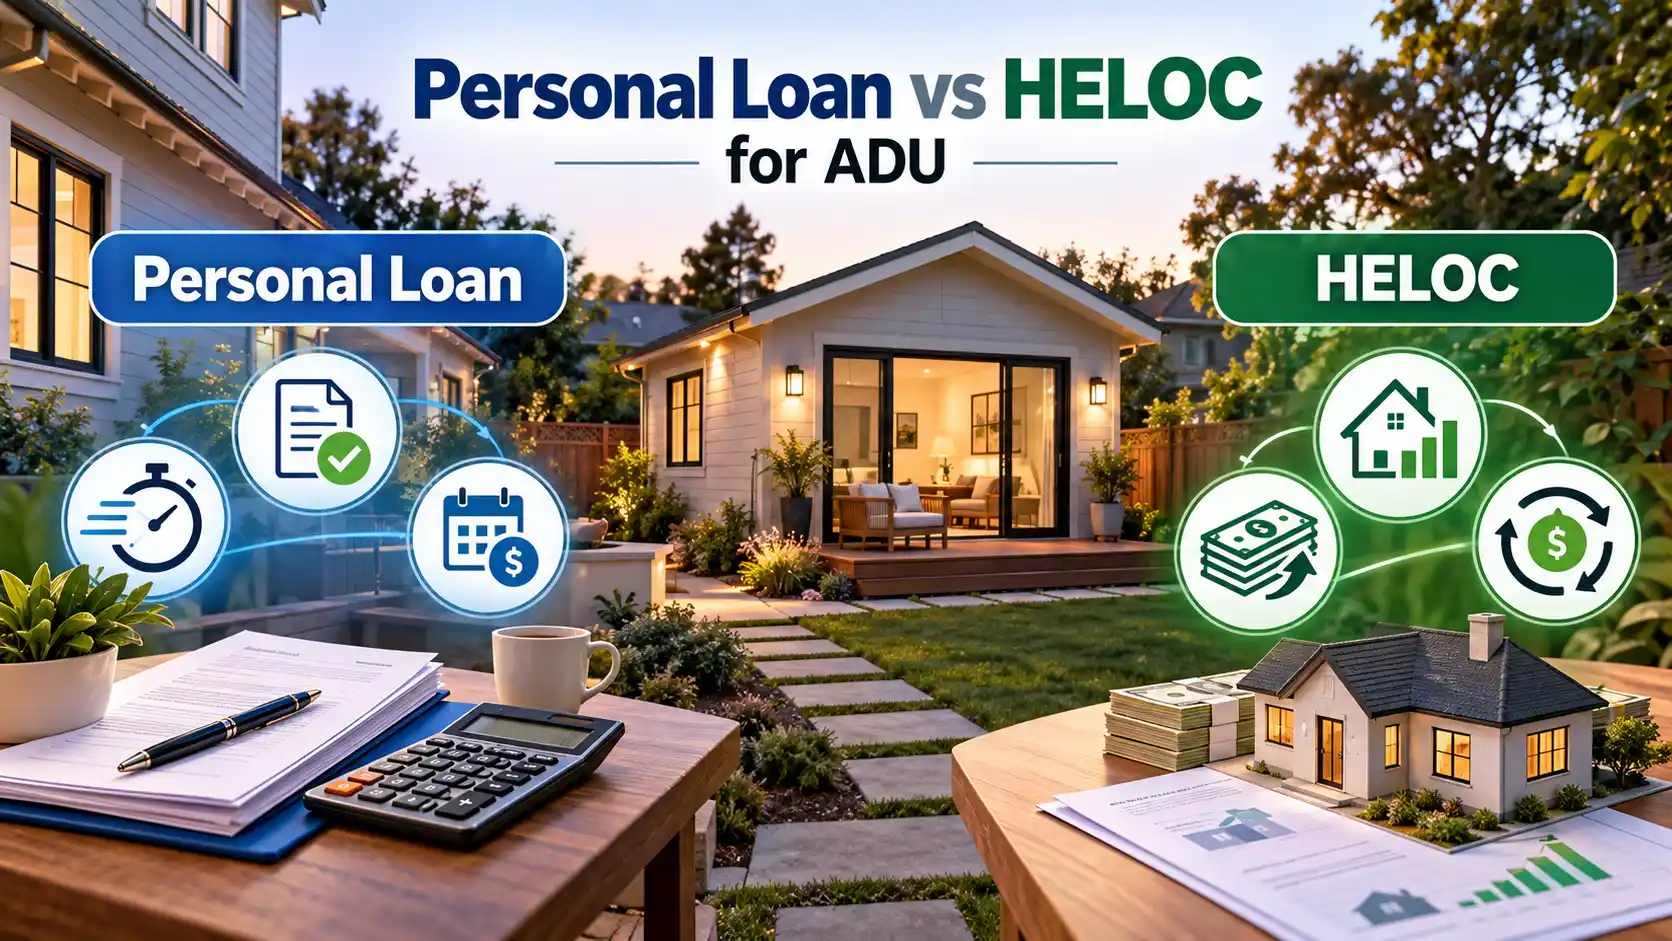
For most backyard cottages, a HELOC costs less over time because it is secured by your home, is usually priced lower and charges interest only on what you draw. A personal loan can cost less when the amount is modest and repaid quickly, because it skips appraisal and closing costs. Amount, repayment time and rate risk decide the winner.
That short answer hides a lot of nuance. The two products are built differently, they reach your account on different timelines, and they behave differently over a decade of payments. This article compares them strictly on the factors that move total cost for an ADU. For the wider menu of options, including construction loans and refinancing, see the complete ADU financing overview.
The Core Difference: What Stands Behind the Loan
A HELOC is secured by your house. The lender holds a lien behind your first mortgage, which lowers its risk and is the main reason HELOC pricing tends to be lower than unsecured lending.
A personal loan is unsecured. The lender relies on your credit history and income alone, so it charges more for the same dollar borrowed and usually caps how much it will lend. The upside is that your home is not pledged, no lien is recorded, and nothing about your property needs to be documented.
Everything else in this comparison flows from that difference: speed, size, fees and how cost grows over time. If you are still deciding between a credit line and other ways to tap equity, our guide to HELOCs, home equity loans and cash-out refinancing covers that choice.
Speed From Application to Funds
A personal loan is usually the faster product. Many lenders show offers after a soft credit inquiry, verify income electronically and fund within days of approval. There is no appraisal and no title work.
A HELOC takes longer because the lender must value the property, check title and record the lien. That timeline rarely matters for an ADU, since design and permitting take months and the first large construction invoice is not due until work starts. It matters more if a personal loan is being considered only because it is faster; for an ADU, speed is seldom worth a higher lifetime cost.
How Far Each One Stretches Against an ADU Budget
A detached ADU is a new home with a foundation, utilities and a full set of systems. Personal loan limits are generally set for smaller projects, so a personal loan on its own often covers only part of the budget.
A HELOC is sized from your equity and income, so homeowners with substantial equity can often cover most or all of the build with a single line. When the budget is large, the comparison often ends here: if a personal loan cannot reach the amount you need, the question becomes how to combine it with something else, not which one to choose. The ADU cost calculator gives a first budget range to measure each product against.
Fixed Payments Versus a Rate That Moves
Personal loans almost always carry a fixed rate and a fixed term. You know the payment and the payoff date on the day you sign, and nothing in the market can change them.
Most HELOCs carry a variable rate tied to an index. When rates fall, your cost falls; when they rise, it rises, and over a long draw and repayment period both can happen. Some lenders let you lock part of a HELOC balance at a fixed rate, which narrows the gap. If certainty is worth paying for, a personal loan’s fixed rate has real value, even when its starting rate is higher.
Up-Front Costs: Closing, Appraisal and Origination
HELOCs can involve appraisal, title, recording and other closing costs, although some lenders reduce or absorb them under certain conditions. Some also charge an annual fee or a fee for closing the line early.
Personal loans skip most of these but may charge an origination fee, often deducted from the amount you receive. When comparing offers, convert every fee into total dollars over the period you actually expect to borrow. A fee that looks small on a large HELOC can disappear over a long payoff, while the same fee on a small personal loan repaid quickly can make it more expensive than it first appears.
Why the Calendar Matters More Than the Rate
Total Interest Grows With Every Year the Balance Stays Open
Interest is charged on the outstanding balance for each period it remains outstanding. A lower rate held for many years can produce more total interest than a higher rate paid off quickly. The comparison that matters is total dollars paid by the time the balance reaches zero, not the starting rate.
Interest-Only Payments Can Stretch the Timeline
A HELOC’s draw period often allows interest-only payments. That keeps early payments low, but if you only pay interest, the balance does not shrink and the total cost keeps climbing. A HELOC used with steady extra principal payments behaves very differently from one left at the minimum.
Short Terms Favor Personal Loans
Personal loans amortize from the first payment over a set term. Every payment reduces the balance, so the loan cannot quietly run for years. For a homeowner who wants a firm payoff date and will not carry the debt long, that discipline is part of the value.
When the Unsecured Loan Is the Cheaper Choice
The amount is small relative to the project, such as finishes, appliances or a final gap.
You plan to repay within a short period, for example from savings that become available or from a bonus.
You have limited equity, or you prefer not to place a lien on the house.
You value a fixed payment and a known payoff date more than the lowest possible rate.
The HELOC’s closing costs would be large relative to the amount you actually need.
Situations That Favor Drawing on Home Equity
The ADU budget is large and will be repaid over many years.
You want to borrow in stages, matching draws to the builder’s invoices so interest runs only on money already spent.
Your home has enough equity to cover the build, and your current mortgage terms are worth protecting.
You expect rental income from the unit to support payments over the long term.
You are comfortable with a variable rate, or your lender offers a fixed-rate lock on part of the balance.
Using Both on One Project
Combining the two is common and often sensible. A HELOC carries the main construction draws, and a smaller personal loan or a promotional offer covers finishes or a shortfall near the end of the build. The personal loan is then the first debt to pay down, while the HELOC is retired over a longer horizon.
Before taking both, check how the combined monthly obligation looks on paper, because each lender considers your other debts. The order matters too: opening the HELOC first usually keeps its approval cleaner. Our article on deferring ADU costs explains how staged billing and interest-only periods fit alongside these loans, and current partner offers for finishes or a funding gap are on the United Signature financing page.
FAQ
Does a personal loan put my house at risk if I fall behind?
A personal loan is not secured by your home, so the lender cannot foreclose on it the way a mortgage lender can. Missed payments still damage your credit and can lead to collection efforts or court action, so the debt is not risk-free.
Can I pay off either loan early without a penalty?
Many personal loans and HELOCs allow early payoff without a penalty, but not all. Some HELOCs charge a fee if the line is closed within an early period, so read the prepayment and early-closure terms before you sign.
Will taking a personal loan make it harder to get a HELOC later?
It can. A new monthly payment raises your debt-to-income ratio, which lenders weigh when approving a HELOC, so if you need both, it is usually smoother to apply for the HELOC first.
What if my HELOC application is turned down?
Ask the lender which factor caused the denial, since equity, income and credit history each point to a different fix. A construction loan underwritten on the completed project’s appraised value, or a smaller project scope, may still make the ADU work.
Can the finished ADU raise how much I could borrow on a HELOC later?
Possibly. A completed, permitted unit can increase the appraised value of the property, and a new appraisal may support a larger line, but each lender decides how much of that value it will recognize.